

March 30, 20260
The practice of a “visa run” carries significant risks — not only may you face deportation, but there is also a real risk of losing a substantial portion of the income earned abroad.
The practice of a “visa run” carries significant risks — not only may you face deportation, but there is also a real risk of losing a substantial portion of the income earned abroad.
For mandatory social security contributions of a founder, expenses recorded in the accounting books are recognized in the tax balance exclusively in the period when the contributions are actually paid. Accrued but unpaid contributions are not recognized as expenses. If payment is late, any interest or penalties are not recognized as expenses, regardless of when they are paid.
A taxpayer who realizes a capital gain or loss from the transfer of digital assets during the year is required to file a tax return for capital gains.
The registry's goal is to streamline the system of fees, charges, and other payments that citizens and businesses make outside of taxes.
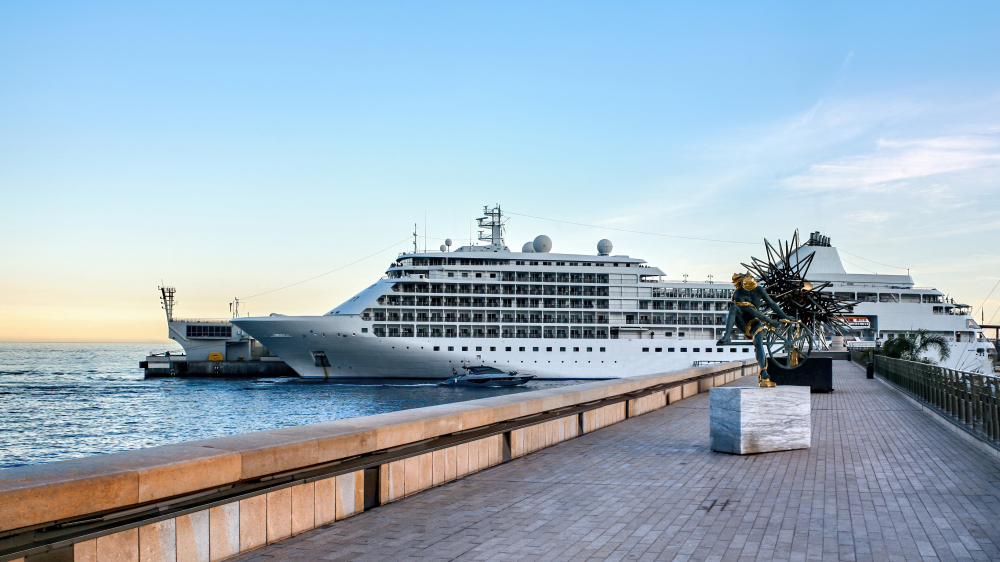
As of 1 January 2025, a revised tax regime applies in Serbia to the income of seafarers working on ships and other vessels flying a foreign flag. The new rules concern individuals engaged as crew members or auxiliary staff and introduce a different approach to determining tax liabilities.

In Serbia, the annual personal income tax applies to individuals whose total income during the calendar year exceeds three times the average annual salary per employee. Essentially, this is an additional tax paid once a year, covering all individuals with above-average income, while those earning below this threshold are exempt. The taxable income threshold is updated annually according to official salary statistics.
Expenses include costs arising from the normal operations of a business, as well as losses that are not necessarily related to revenue generation. Examples of normal operating costs include cost of goods sold, employee salaries, and equipment depreciation.
Predominant exporter status plays an important role within the VAT system, primarily due to different VAT refund deadlines in situations where the amount of input VAT exceeds the amount of VAT liability and the taxpayer opts for a VAT refund.
According to the Law on Personal Income Tax, new standardized expense amounts have been published, directly affecting tax and contribution obligations.
For all entrepreneurs operating under the flat-rate (paušal) system, the Serbian Tax Administration has already calculated taxes and contributions for 2026.


